An investment firm with 30 advisers, an insurance broker with 20 appointed representatives and a two-director credit broker. Different permissions, different pressures, one platform.
A compliance team of two, keeping pace with a growing adviser force.
Read the case study →A principal firm that needs to prove its oversight, not just carry it out.
Read the case study →Compliance that fits around running the business, and stands up to lender audits.
Read the case study →The firm advises retail clients on investments and pensions and runs a discretionary service alongside. The adviser force had doubled in five years. The compliance function had not.
Checks for suitability file reviews, PA dealing, market abuse and client categorisation, each with an owner, a due date, findings and remediation actions. Rule Map lays out the COBS and MIFIDPRU rules alongside, to be confirmed section by section.
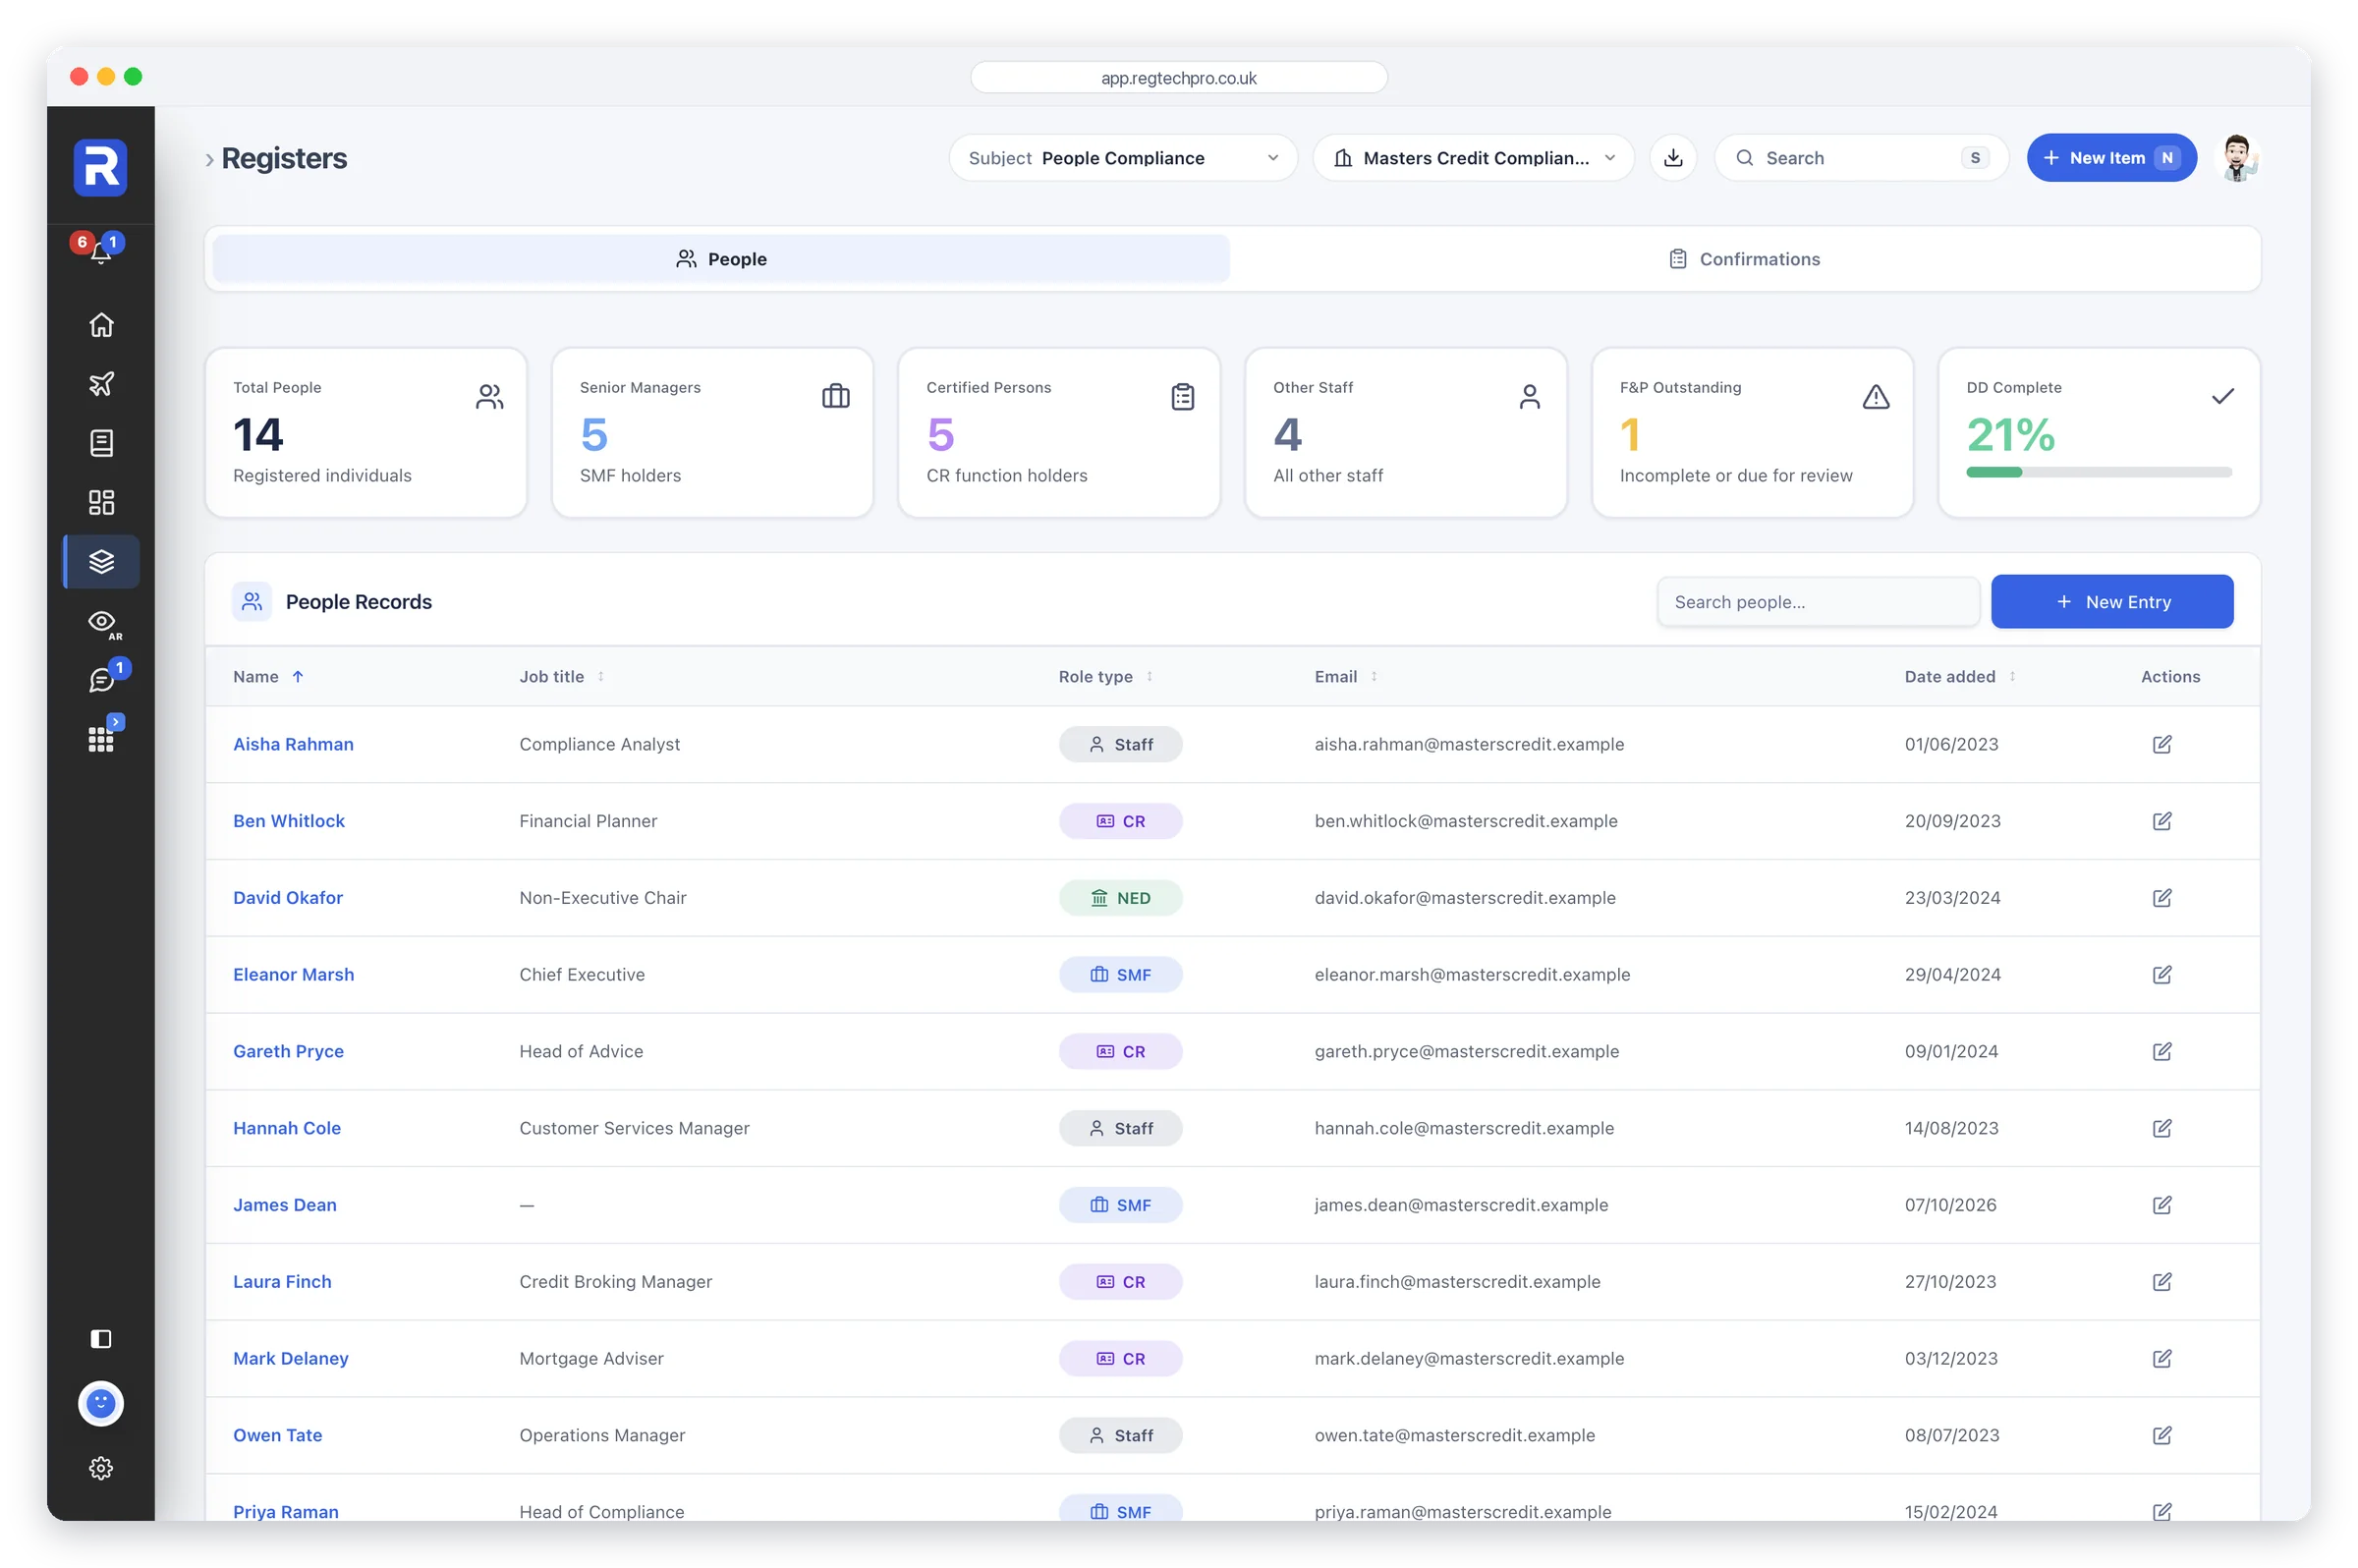
Every adviser holds a fit and proper assessment, certification function and CPD record against their target. Senior managers carry a Statement of Responsibilities.
Every promotion is logged in the register, reviewed against COBS 4 and approved on the record, alongside complaints, breaches, conflicts and gifts.
A fair value assessment for each service, outcome monitoring through the year and a board report built from the firm’s own records, with Otto writing the commentary, for the directors to review and approve.
The feed is filtered to investments. Each relevant publication is logged with the firm’s assessment and the action taken, so the audit trail writes itself.
The team starts the week on everything overdue, due or waiting on them. Each quarter the directors receive the Compliance Position report, built from live records.
The principal firm arranges general insurance and protection through its own office and a network of 20 appointed representatives, from single-adviser brokerages to offices of eight. Under SUP 12, the principal is responsible for everything its ARs do.
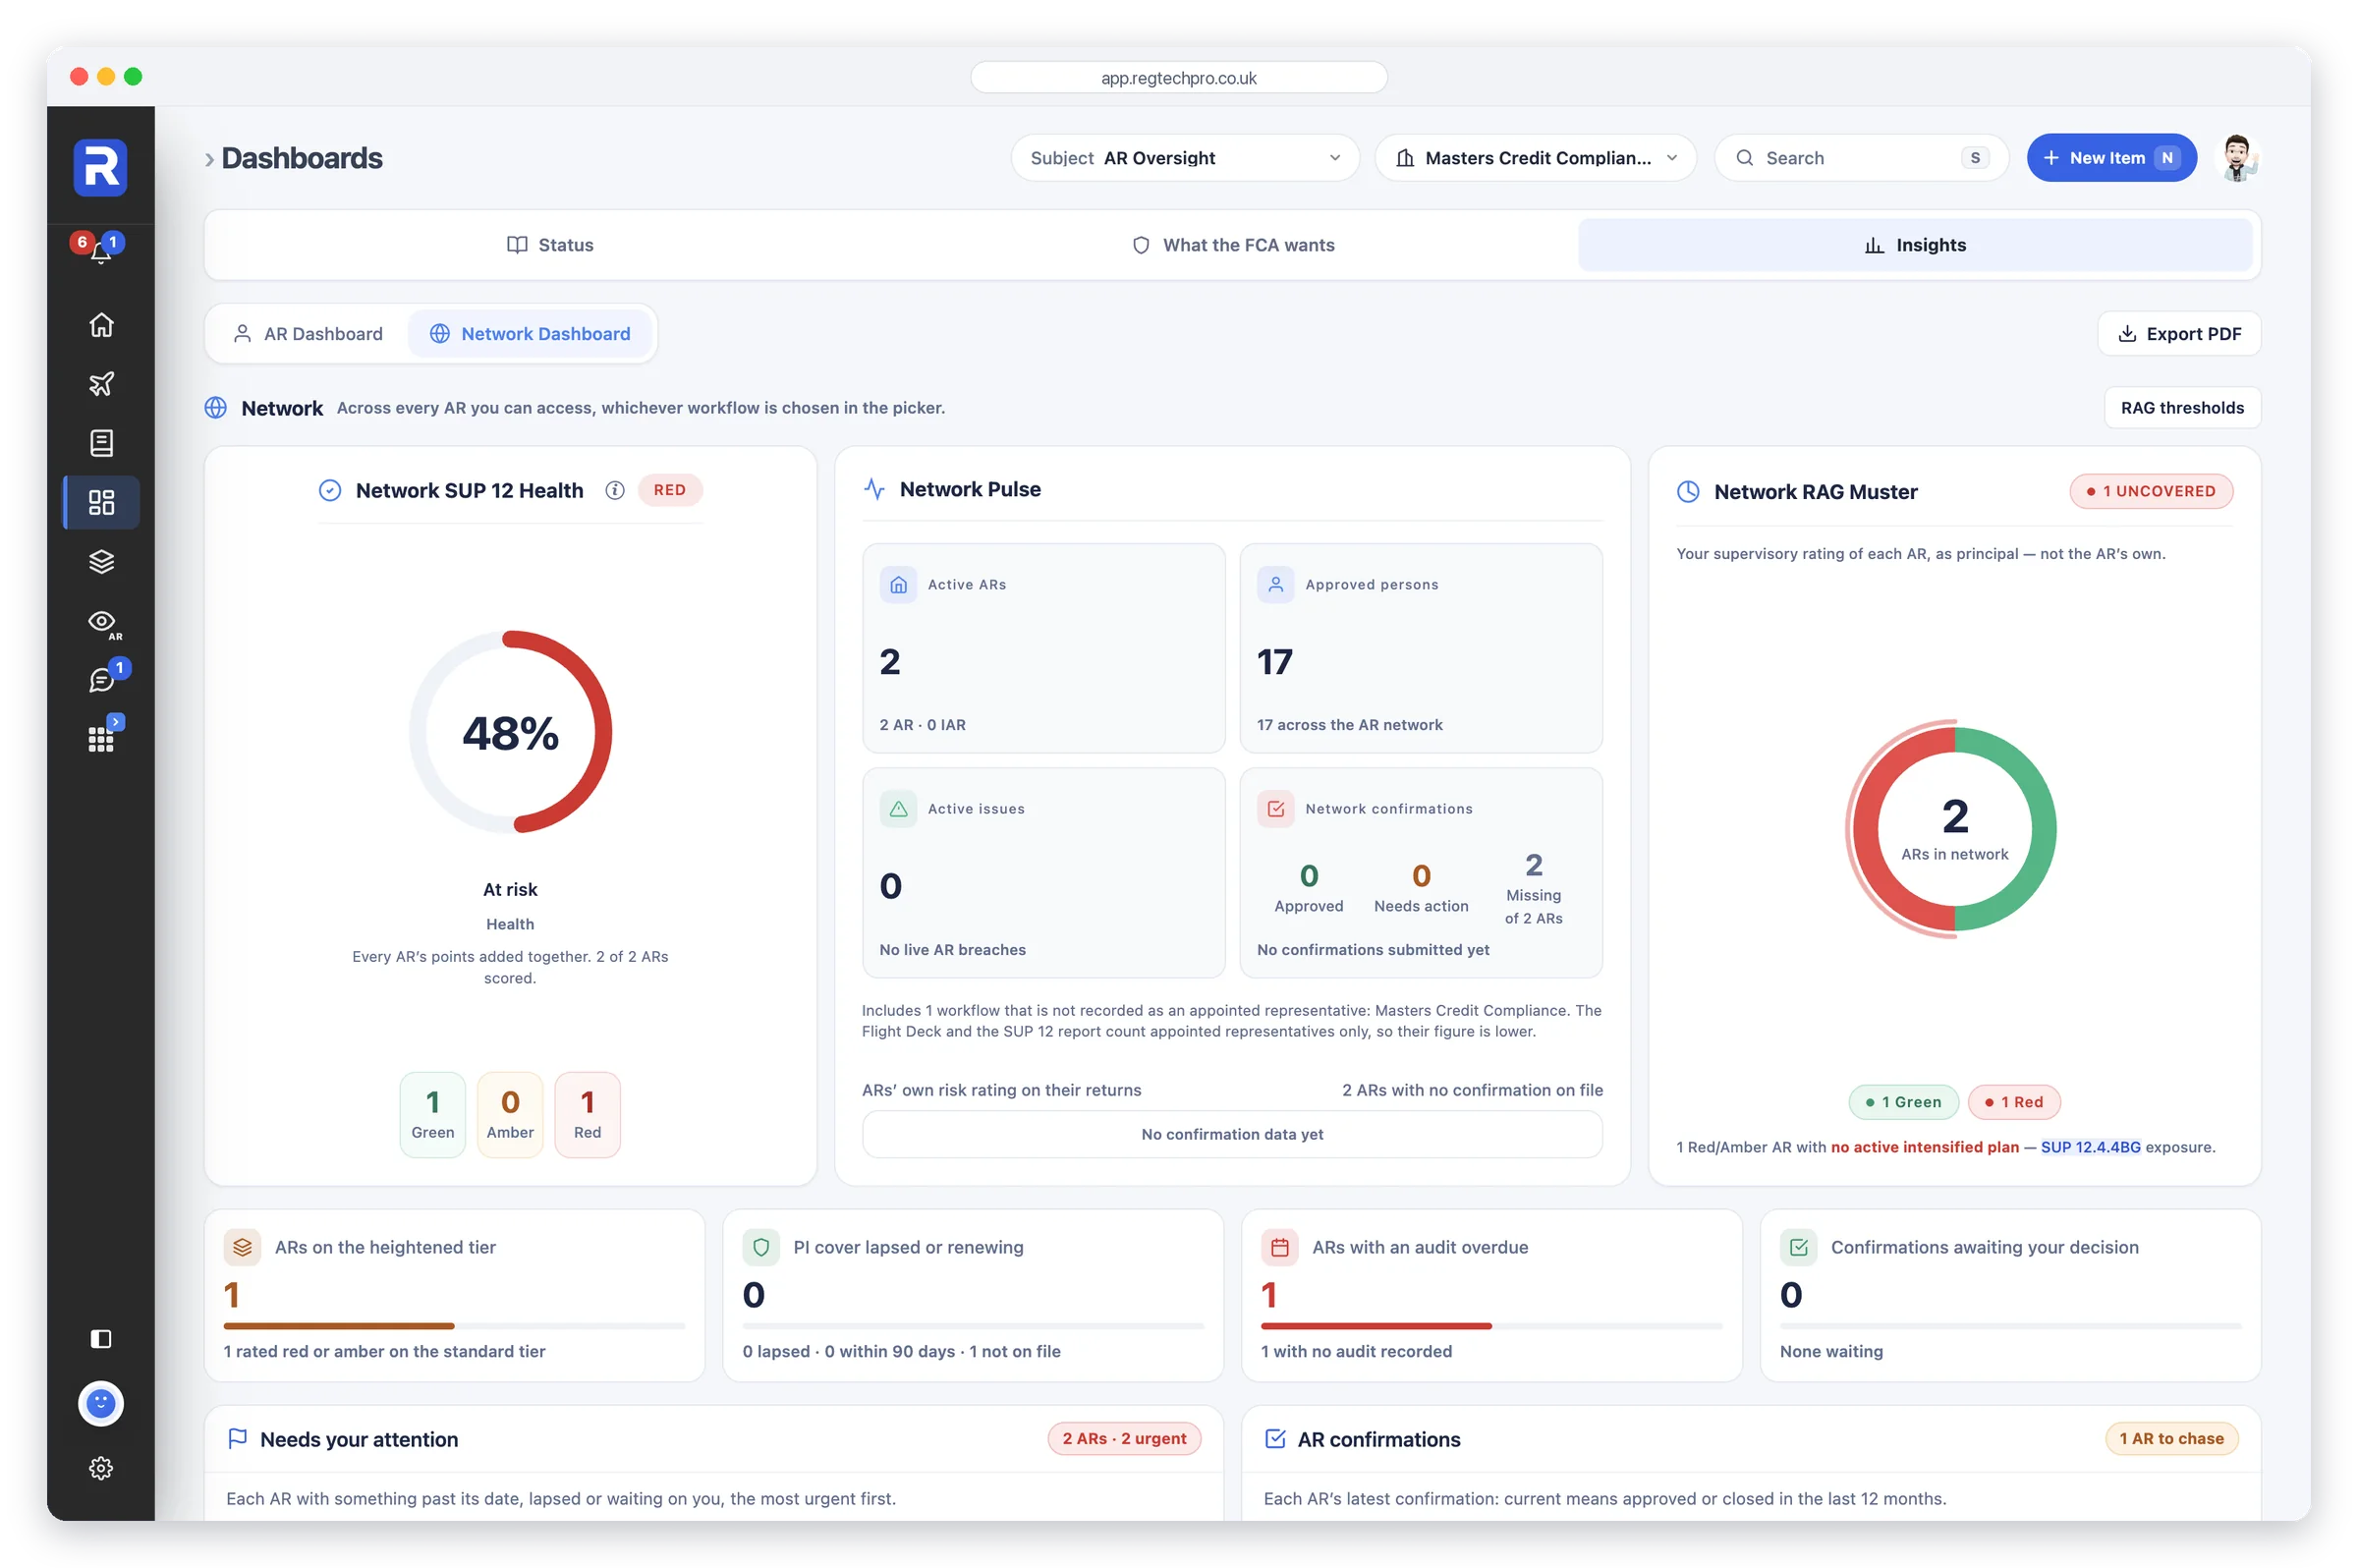
The Network Dashboard shows the RAG muster, the ARs that need attention, the AR confirmations to chase, PI cover renewals, and complaints across the network.
Each AR has an onboarding due diligence pack with documents that flag themselves for renewal, and an appointment decision with the approving senior manager named.
Supervisory meetings, customer file sampling, second-line reviews and intensified monitoring for higher-risk ARs, each with its findings and outcome on the record.
Each AR signs in to its own portal: its confirmations and register entries, its firm record, its people and its documents. The principal reviews and approves rather than collects.
Communication is attached to the tasks it concerns, and an approvals inbox holds everything waiting on the principal’s sign-off.
The SUP 12 Report sets out the firm’s oversight for the board pack or an FCA review, and supports the annual SUP 12 review.
The firm introduces customers to a panel of lenders for vehicle and home improvement finance. One director runs sales; the other holds compliance oversight alongside finance and operations. There’s no compliance department, and no appetite for one.
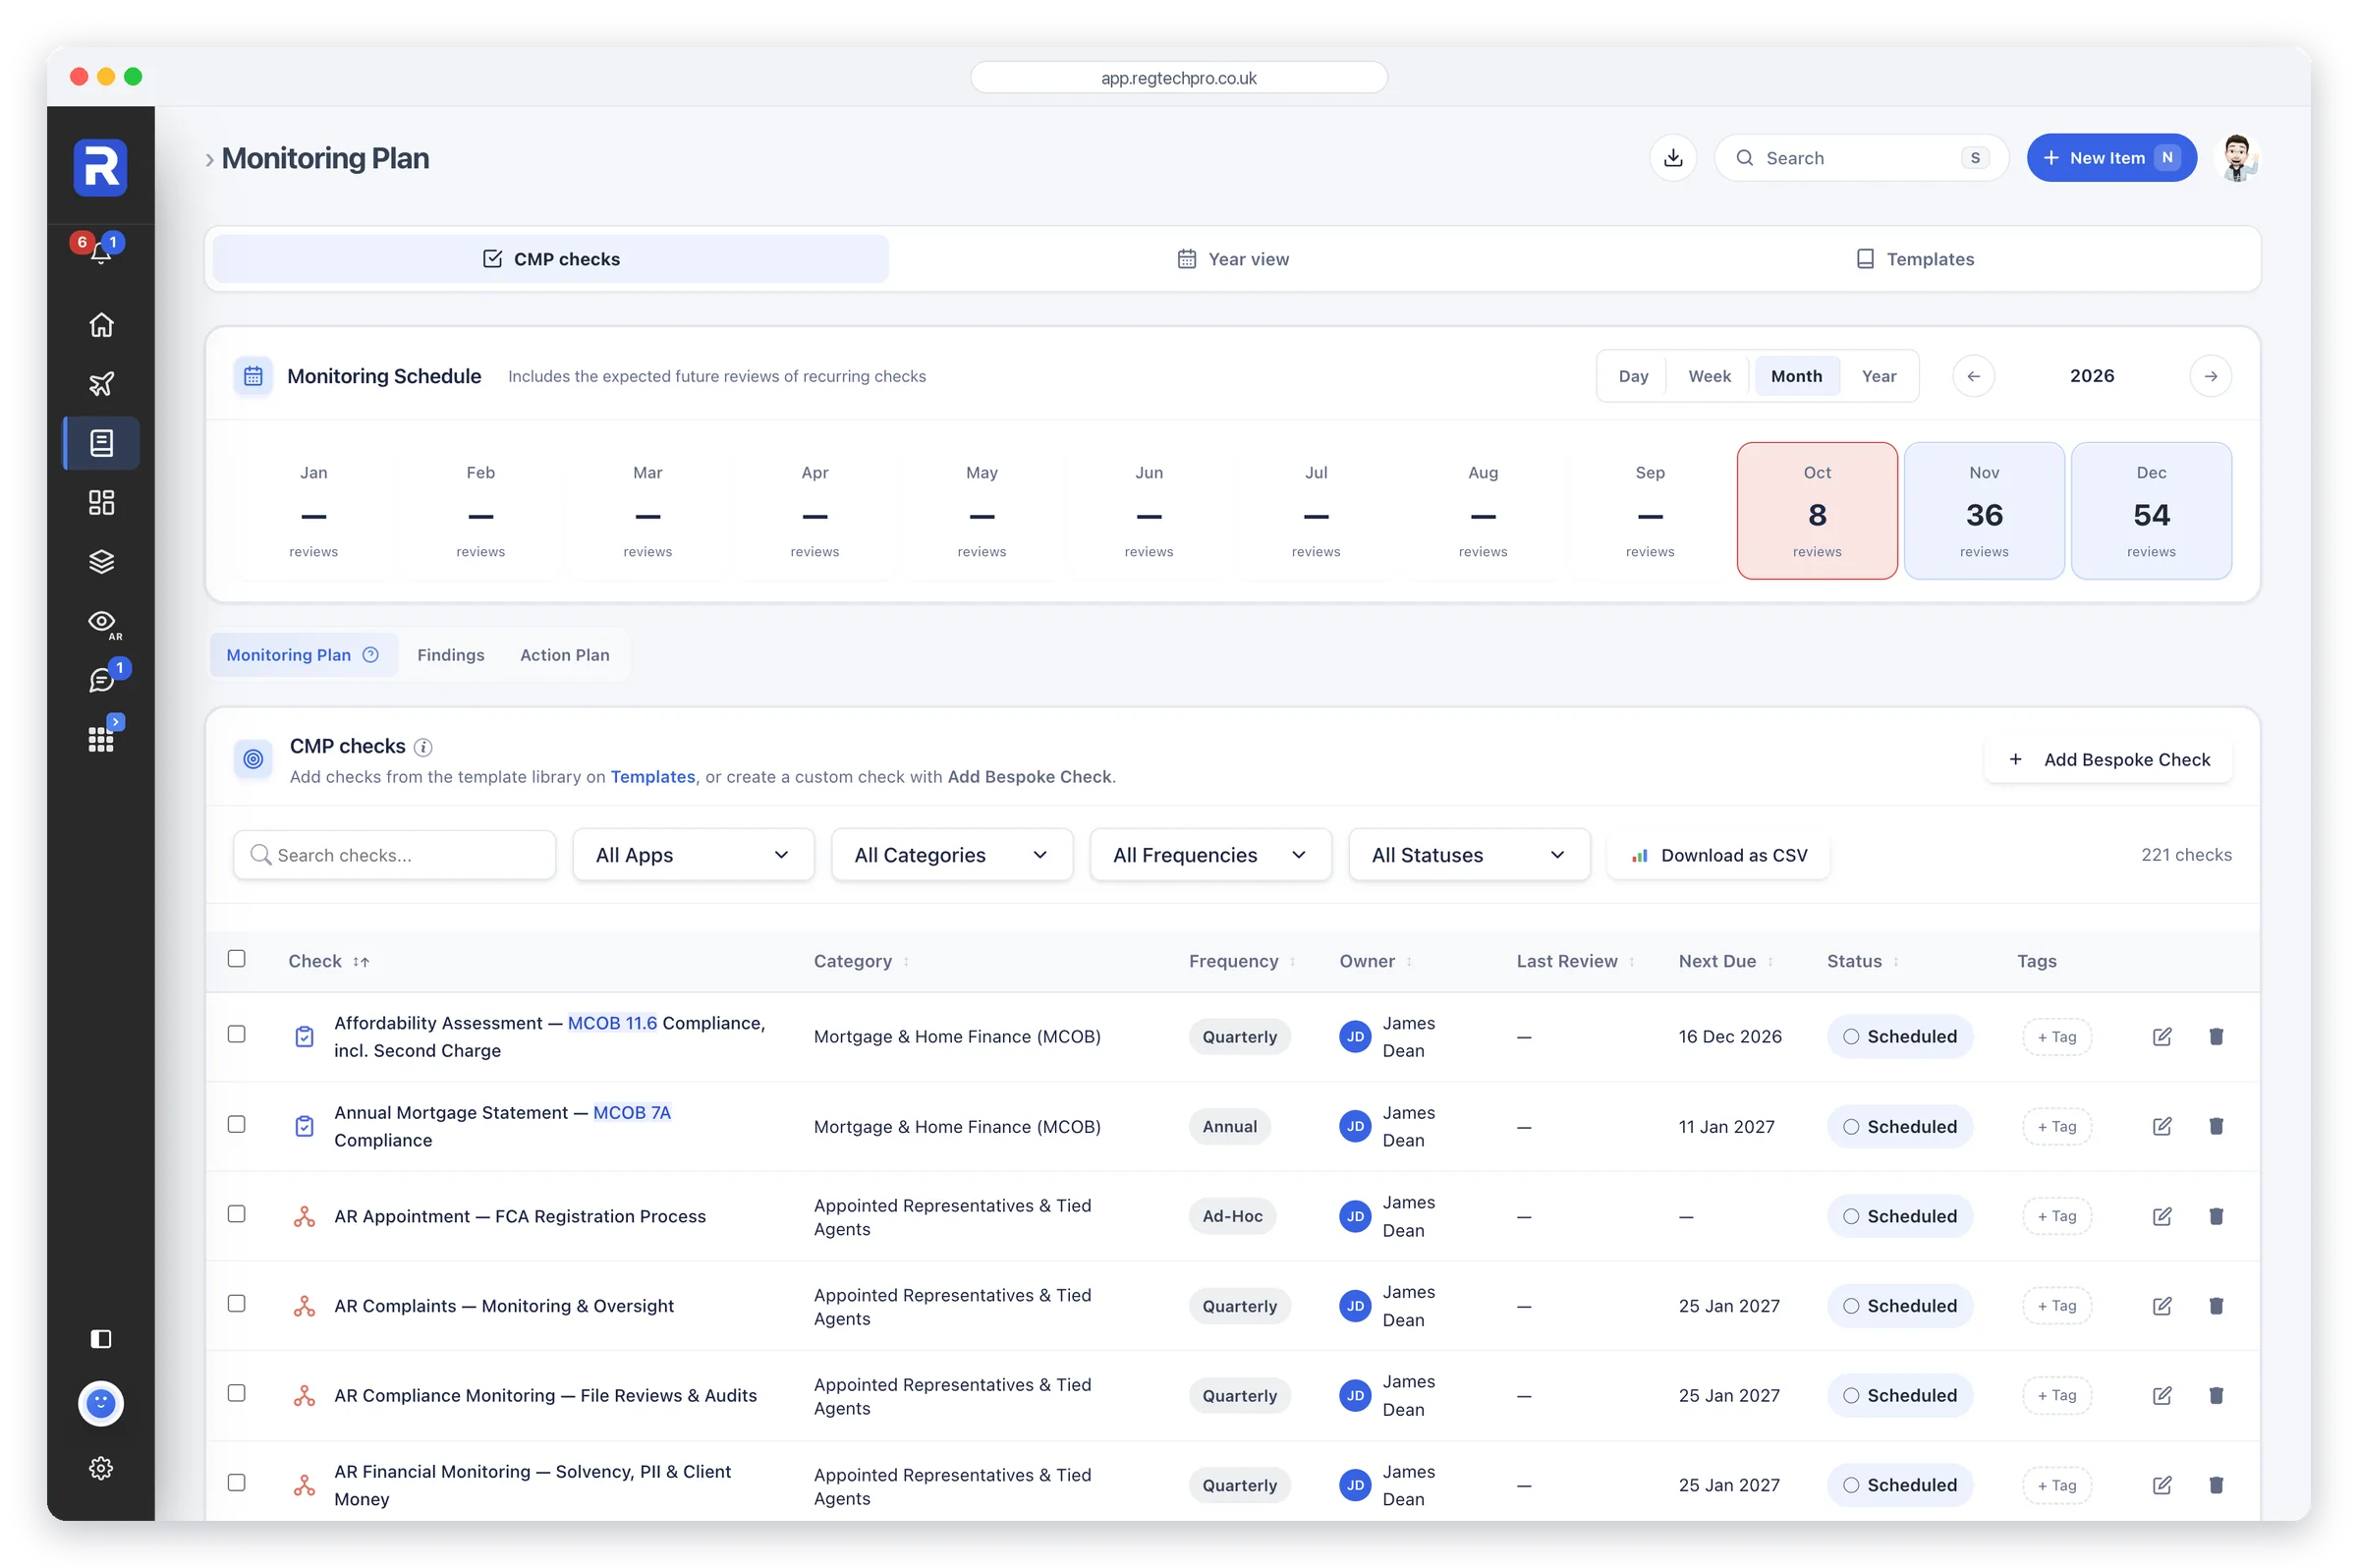
Consumer credit monitoring checks are scheduled across the year, so the compliance director works through a few each week rather than everything at once.
The financial promotions register holds each piece, the CONC review and the sign-off. Complaints and breaches are logged in the same place, and Rule Map lays out the CONC rules, to be confirmed section by section.
Fair value, customer understanding and support are assessed for the firm’s services, and the annual board report is built from those records, with Otto writing the commentary, for the directors to review and approve.
The firm tailored its policies from expert templates, approved them on the record and reviews them on a set cycle.
Fit and proper assessments, responsibilities, training and CPD, ready to hand to a lender when asked.
Updates are filtered to consumer credit. When a question comes up about a CONC rule, the directors ask Otto and get an answer cited to the Handbook.
We use essential cookies to make the site work, and optional analytics cookies to understand how it's used. See our Cookie Policy.